Private equity fund structures look complicated from the outside, and some of that complexity is real. Most of it, though, follows a small number of patterns that repeat from fund to fund. A Limited Partner who understands those patterns can read a PPM or an LPA quickly, see where a manager has departed from the market, and spend negotiating time on the terms that actually move returns.
This guide covers the parts that matter most to an LP.
- How a fund is structured and why it is set up that way
- The legal entities involved and the role each one plays
- Market-standard terms and where there is room to negotiate
- The documents you will be asked to review and sign
- How capital moves through the fund over its life
- The rights and protections available to LPs
It is written for investment teams at pension funds, insurers, funds of funds and family offices, whether you are building a private markets programme or have been investing in the asset class for decades.
How a fund is structured
Most private equity funds are set up as limited partnerships. The structure has lasted because it does three things well. It aligns the interests of the manager and the investors, it is tax transparent in most jurisdictions, so investors are taxed as if they held the underlying investments directly, and it limits each investor's liability to the capital they have committed.
The entities involved
| Entity | Role | Purpose |
|---|---|---|
| Limited Partnership (the fund) | Investment vehicle | Pools investor capital and holds the investments |
| General Partner | Manager of the partnership | Makes investment decisions and carries unlimited liability |
| Limited Partners | Investors | Commit capital and take a passive role |
| Management Company | Operating entity | Employs the investment team and runs day-to-day operations |
Limited Partners commit capital to the partnership, and the General Partner decides how it is invested. The General Partner is usually a special purpose entity owned by the senior members of the manager. It delegates the day-to-day work to a Management Company, which employs the investment professionals and receives the management fee.

Separating the General Partner from the Management Company keeps the unlimited liability of the General Partner inside a vehicle with no other business, and lets the manager run several funds from one operating company.
Common structural variations
The basic model stays the same, but funds adapt it to suit the investors they want to admit and the regulation they operate under.
A single limited partnership is common for funds raising from one market, for example a Delaware limited partnership for a US investor base or a Luxembourg SCSp for European investors.
A master-feeder structure pools capital from investors with different tax and regulatory needs. Feeder funds collect commitments from each investor group and invest into a single master fund, which makes the investments. A typical arrangement uses a Delaware feeder for US taxable investors and a Cayman Islands or Luxembourg feeder for non-US and tax-exempt investors.
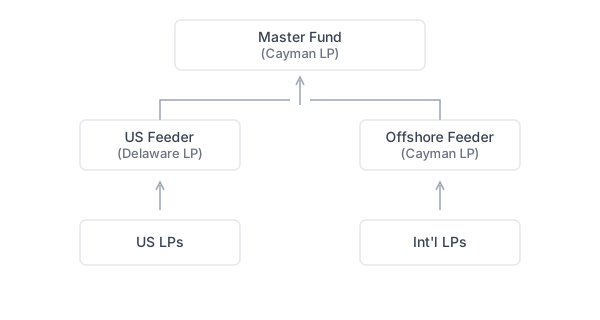
Parallel funds invest alongside the main fund, in the same deals and in fixed proportions, for investors who cannot or prefer not to invest through the main vehicle. Costs and returns are shared pro rata.
Alternative investment vehicles are set up for individual deals when the structure of a particular investment would create tax or regulatory problems for some investors in the main fund.
Choosing a domicile
Where a fund is domiciled affects its tax treatment, the regulation that applies to it and the investors it can reach.
- Delaware remains the default for funds raising mainly from US investors, with a well-tested legal framework that most investors already know.
- The Cayman Islands is the most widely used offshore domicile, chosen for its tax neutrality and its flexibility for non-US investors.
- Luxembourg is the leading European domicile. The SCSp partnership, often combined with a RAIF, gives managers access to investors across the EU through the AIFMD marketing passport.
- Ireland, with its Investment Limited Partnership, and the United Kingdom, with the English limited partnership, are the other common choices for European funds.
Larger managers often combine several of these, with a main fund in one jurisdiction and feeders or parallel funds in others.
Market-standard fund terms
Decades of fundraising have produced a set of terms that most funds start from. The traditional "2 and 20", a 2% management fee and 20% carried interest above an 8% preferred return, is still the benchmark, although actual terms shift with market conditions and the negotiating strength of each manager.
| Term | Market standard |
|---|---|
| Management fee | 1.5 to 2% of commitments during the investment period |
| Fee after the investment period | Steps down, usually to a percentage of invested capital |
| Carried interest | 20% of profits |
| Preferred return | 8% a year, with a GP catch-up |
| GP commitment | 1 to 2% of total commitments, sometimes more |
| Fund term | 10 years, with one or two one-year extensions |
| Investment period | 4 to 6 years |
The distribution waterfall decides when the General Partner receives carried interest. Under a whole-fund (European) waterfall, LPs receive all contributed capital and the preferred return before any carry is paid. Under a deal-by-deal (American) waterfall, carry can be paid on each realised investment, which brings the manager's payout forward and makes a strong clawback provision essential. The difference can change the timing of an LP's cash flows by several years.
Headline terms only mean something against the market. A 2% fee on a first-time mid-market fund and a 2% fee on a manager's fifth large buyout fund are very different propositions. FundFrame's Due Diligence reads each PPM your team receives and sets the fund's fees, carry and terms against every fund you have reviewed before, so an off-market term stands out before the first meeting.
To see how fees and carry interact as a manager's funds grow, the PE Fund Economics Calculator models GP economics across fund sizes and the returns needed to keep interests aligned with LPs.
How capital moves through the fund
A fund's life follows a predictable sequence, and each stage has its own cash flows for the LP.
Fundraising and first close
The General Partner sets up the structure and markets the fund, and investors sign subscription documents. Capital is committed rather than paid in at this stage. Later investors are usually admitted at subsequent closes and pay an equalisation amount so that they carry their share of the costs and investments made so far.
Investment period
The General Partner calls capital from LPs as it makes investments and to pay fees and expenses, usually with ten business days' notice. Many funds use a subscription credit line to bridge investments before calling capital, which smooths the calls but can flatter the fund's reported IRR. Management fees are normally charged on committed capital during this period.
Holding and harvest period
Once the investment period ends, new investments stop apart from follow-ons in existing portfolio companies. The manager works on value creation and then exits, and the proceeds are distributed to LPs through the waterfall. The management fee usually steps down to a percentage of invested capital.
Across a portfolio of funds, these calls, distributions and quarterly capital account statements add up quickly. FundFrame's Portfolio Monitoring reads each statement and report as it arrives, books the cash flows against the right fund and keeps every figure linked to the page it came from. We have written more about processing capital account statements separately.
Key fund formation documents
A fund is governed by a set of legal documents that together define the economics, the governance and the obligations of each party for the fund's whole life.
| Document | Purpose | Key elements |
|---|---|---|
| Private Placement Memorandum (PPM) | Marketing and disclosure | Strategy, team, track record, summary of terms, risk factors |
| Limited Partnership Agreement (LPA) | Primary governing document | Economic terms, governance, investment restrictions, waterfall |
| Subscription Agreement | Admits the LP to the fund | Commitment amount, investor status, tax and regulatory representations |
| Side Letters | Terms for individual LPs | Reporting, fee arrangements, regulatory needs, MFN rights |
| Investment Management Agreement | Appoints the manager | Services, fees, expense allocation, termination rights |
Private Placement Memorandum
The PPM is usually the first document an LP reads. It describes the strategy, the team and the track record, and summarises the proposed terms. It is a marketing document, so the track record and the terms both need checking against the underlying data and, later, against the LPA.
Limited Partnership Agreement
The LPA is the fund's constitution. It sets the economic terms and the waterfall, the powers of the General Partner, the investment restrictions and the rights of LPs. LPAs have grown longer over the years, but the sections that deserve the most attention are consistent from fund to fund. They cover fees and expenses, the waterfall and clawback, key person provisions, removal of the General Partner, and conflicts of interest.
Subscription Agreement
The Subscription Agreement is how each LP is admitted to the fund. It records the commitment, confirms that the investor is eligible, and contains the representations needed for tax, anti-money laundering and regulatory purposes.
Side Letters
Side Letters give individual LPs terms that do not belong in the LPA, such as additional reporting, restrictions on certain investments or provisions that a regulated investor needs. Most favoured nation clauses then let other LPs elect terms given to investors of the same or smaller size. Keeping track of what was agreed with each manager, and why, matters again when the manager returns with the next fund. An investment CRM keeps those negotiations and your team's decisions on the manager's record.
Investment Management Agreement
The Investment Management Agreement sets out the relationship between the fund and the Management Company, including the services provided, the fee and how expenses are allocated between the manager and the fund. Expense allocation has drawn close regulatory attention, and it is worth reading alongside the LPA.
What to look for as an LP
When you review a fund's structure and terms, four questions cover most of what matters.
- Alignment. Do the fee base, the waterfall and the size of the GP commitment reward the manager for returns rather than for asset growth?
- Complexity. Does each additional vehicle or layer have a clear tax or regulatory reason, or does it mainly add cost and opacity?
- Governance. Does the LPAC have real authority over conflicts, and are the key person and GP removal provisions workable in practice?
- Fit. Can the structure accommodate your own tax position, regulatory requirements and reporting needs?
Structure is one part of manager selection. We have written about a systematic approach to manager selection and about comparing funds against vintage benchmarks.
Where structures are heading
The core limited partnership model has changed little, but the arrangements around it continue to develop. Continuation vehicles and other GP-led secondaries now give managers a way to hold assets beyond a fund's term. Evergreen and semi-liquid structures are opening private markets to new investor groups. NAV facilities add leverage at the fund level. At the same time, regulation such as AIFMD II and ILPA's reporting templates is pushing towards more consistent disclosure of fees and expenses.
Each of these adds terms for LPs to read, compare and monitor. The fundamentals in this guide remain the place to start.
Essential private equity fund terms
Structure
| Term | Meaning |
|---|---|
| Limited Partnership | The fund vehicle that pools investor capital and makes investments, with liability for LPs limited to their commitment |
| General Partner (GP) | The entity that manages the partnership and makes investment decisions, carrying unlimited liability |
| Management Company | The entity that employs the investment team and receives the management fee |
| Feeder Fund | A vehicle that collects capital from a group of investors and invests it into a master fund |
| Parallel Fund | A separate vehicle investing alongside the main fund in fixed proportions |
| Side Letter | A separate agreement giving an individual LP specific terms or rights |
Economics
| Term | Meaning |
|---|---|
| Management Fee | The annual fee paid to the manager, usually on commitments and then on invested capital |
| Carried Interest | The General Partner's share of profits, typically 20%, paid through the waterfall |
| Preferred Return | The minimum annual return, typically 8%, that LPs receive before carry is paid |
| Catch-up | The share of distributions above the preferred return that goes to the GP until it has received its full carry |
| Waterfall | The order in which proceeds are distributed between LPs and the General Partner |
| GP Commitment | The General Partner's own investment in the fund, typically 1 to 2% of commitments |
| Clawback | The obligation on the General Partner to return carry it has received in excess of its entitlement |
Operations and governance
| Term | Meaning |
|---|---|
| Capital Commitment | The amount an LP agrees to invest over the life of the fund |
| Capital Call | A request from the General Partner for LPs to pay in part of their commitment |
| Distribution | A payment to LPs of capital and profits from realised investments |
| LPAC | The Limited Partner Advisory Committee, which advises on conflicts and other matters set out in the LPA |
| Most Favoured Nation (MFN) | A right to elect terms given to other LPs in their side letters |
| Key Person Provision | A protection that suspends investment if named individuals leave the manager |
Timeline
| Term | Meaning |
|---|---|
| Investment Period | The period, typically 4 to 6 years, in which the fund makes new investments |
| Harvest Period | The period after the investment period in which investments are managed and sold |
| Fund Term | The total life of the fund, typically 10 years plus extensions |
| Extension | An additional period, usually one year at a time, to complete the sale of remaining investments |
| Follow-on Investment | An additional investment in an existing portfolio company |
| Co-investment | A direct investment by an LP alongside the fund in a specific deal |
FundFrame brings the investment CRM, due diligence and portfolio monitoring onto one record for Limited Partners. Book a demo to see it with your own funds.